NOAA forecasts a very strong El Niño this winter. Book a free roof check before the rain →
Infinite Wildfire Defense · a division of Infinite Home Solutions CSLB #1126804 · B · C-39  |  (559) 550-6398

California Homeowners

Your carrier is required to give wildfire discounts. We make your home qualify.

Quick answer: California's Safer from Wildfires regulation requires every admitted insurer, and the FAIR Plan, to discount premiums for specific home hardening actions, and we do the work and build the documentation your carrier needs.

Under California's “Safer from Wildfires” regulation (California Code of Regulations, Title 10, §2644.9), every admitted carrier — and the FAIR Plan — must reduce premiums for 12 specific hardening actions. The FAIR Plan alone offers up to 16.4% off the wildfire portion. We do the work and hand you the documentation file that makes your carrier honor it.

Get Your Free Hardening & Discount Assessment

45 minutes · Your official fire-zone lookup + 12-point insurance discount audit · No obligation
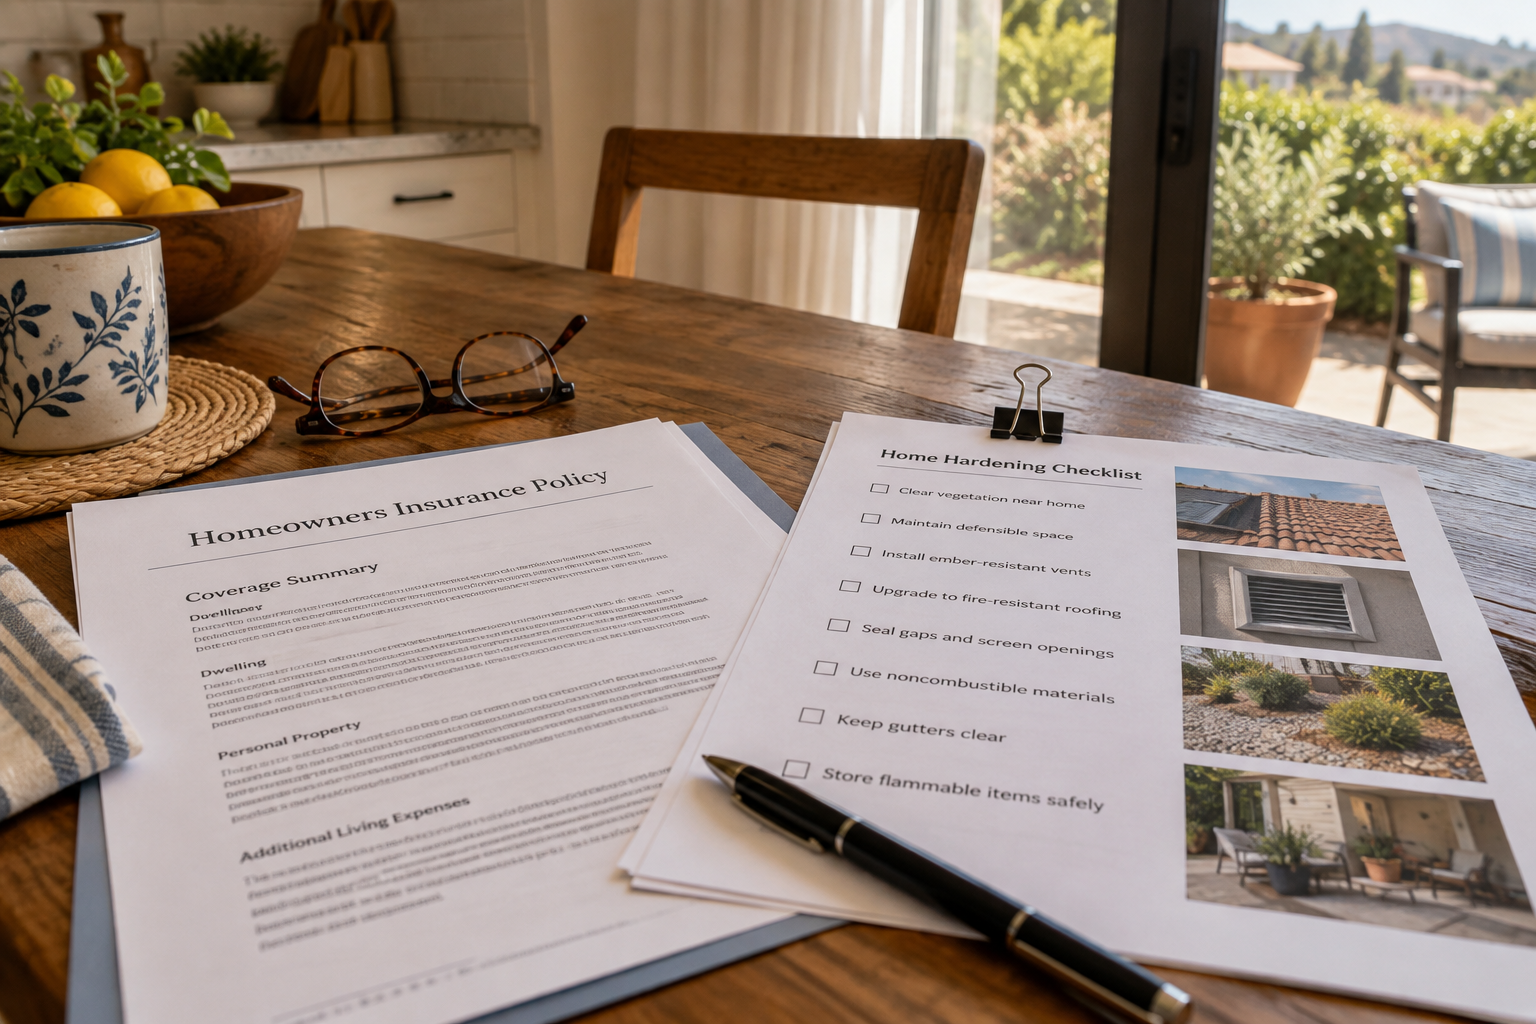
Homeowner's insurance policy next to a home hardening checklist with job photos
The discount conversation goes differently when you bring documentation instead of a description.

Four pools of money — and "my house might burn" isn't one of them

Hardening your home is the only home improvement that pays you back through your insurance bill, every single year.

1. Mandatory discounts

Under the "Safer from Wildfires" regulation (California Code of Regulations, Title 10, §2644.9), your carrier must discount for qualifying hardening — required discounts range 4%–40%, with the largest going to the highest-risk homes. The FAIR Plan alone offers up to 16.4% off the wildfire portion of your premium.

2. Escape the FAIR Plan

Carriers are now required to write policies in wildfire areas — and they pick the documented, hardened homes first. Getting back to a standard carrier is often worth thousands per year.

3. State grant money

California's new Safe Homes program (AB 888) will help pay for fire-safe roofs and the 5-foot ember zone for qualifying homeowners. Assessed homes are ready homes when the portal opens.

4. Resale & compliance

Selling in a high fire-hazard zone now requires defensible-space documentation (AB 38) — and the new statewide Zone 0 rule puts ~2 million homes on a hardening clock. Early movers avoid the rush.

Hardening packages

Every package includes the Insurance Discount File™ — dated photos, receipts, an inspection letter, and the completed 12-point checklist. Carriers honor paperwork, not effort. Financing available through Wisetack on every tier.

Bronze — Discount Ready

~$6,000

  • Zone 0 ember-resistant conversion (0–5 ft)
  • Ember-resistant (WUI-listed) vent replacement
  • Fire-rated gutter guards
  • Combustibles relocated 30+ ft
  • Insurance Discount File™

Financing available — soft-pull prequalification on the spot, no credit impact. Subject to credit approval; terms vary.

Silver — Hardened Home

~$18,000

  • Everything in Bronze
  • Enclosed eaves & noncombustible wall base
  • Window / shutter upgrades
  • Noncombustible fence transitions
  • Zone 1–2 defensible space work

Gold — Certified & Defended

~$40,000

  • Everything in Silver
  • IBHS Wildfire Prepared Home certification path — the standard major carriers are committing to write new policies for
  • Exterior wildfire sprinkler system
  • Annual re-certification visit

Honest fine print, up front: discounts apply to the wildfire portion of your premium and vary by carrier filing. In the foothills that's most of your bill. If you're in a low-risk zone or on a surplus-lines carrier, we'll tell you straight what applies and what doesn't — that's the point of the free assessment.

Founded by a 25-year volunteer firefighter

Fred Warder spent 25 years as a lifetime member of a volunteer fire company before building one of the Central Valley's established roofing and home services contractors.

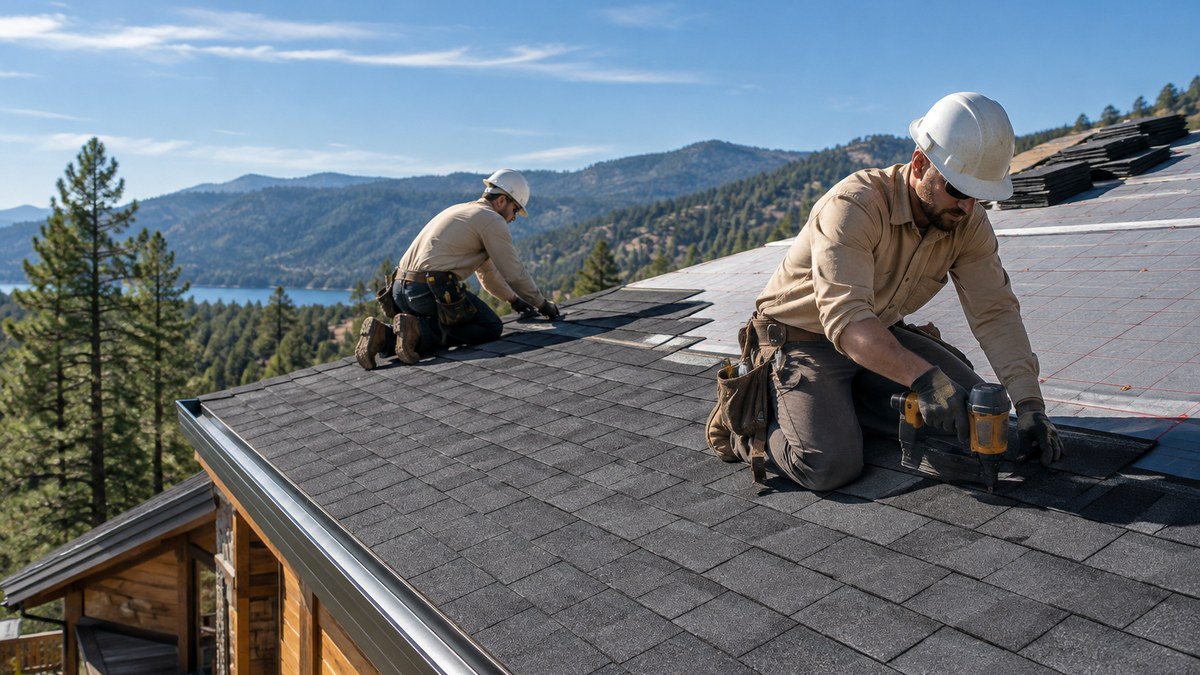
Class A fire-rated roof assembly being installed on a California home
A Class A assembly is the single highest-weighted item in the Safer from Wildfires framework.

Why a licensed contractor — not a landscaper

Most of what insurers actually discount is structural: WUI-listed vents, Class A roofing, enclosed eaves, noncombustible wall base, window upgrades. That's licensed-contractor work. Infinite Home Solutions holds B General Contractor and C-39 Roofing licenses (CSLB #1126804) and has served the Central Valley for over a decade.

Serving the Sierra foothill corridor: Auberry · Prather · Tollhouse · Shaver Lake · North Fork · Oakhurst · Coarsegold · Mariposa · and communities north through the foothills.

What "defensible space" actually means

ZoneDistanceWhat's required
Zone 0 — Ember-resistant0–5 ftNothing combustible: hardscape or gravel, no vegetation or mulch, metal fence transitions. Now California regulation, phasing in for ~2M homes.
Zone 1 — Lean, clean & green5–30 ftSpaced plantings, no ladder fuels, tree limbs up 6–10 ft and 10 ft off the roof.
Zone 2 — Reduced fuel30–100 ftThinning, spacing, grass to 4 inches — to 100 ft or your property line. Already law in most foothill areas; CAL FIRE inspects.
The structure—Class A roof, ember-resistant vents, eaves, wall base, windows, gutters, deck — where the biggest discounts live.

Questions foothill homeowners ask us

Does homeowners insurance cover wildfires in California?

Standard homeowners policies generally cover fire, including wildfire. The challenge in high-risk areas is getting and keeping a policy at all. Many homeowners have been non-renewed and moved to the FAIR Plan, which is why hardening and documentation matter.

Which insurers give wildfire mitigation discounts in California?

Under the Safer from Wildfires regulation, every admitted carrier writing in California, including the large national brands, must offer discounts for qualifying mitigation, and so must the FAIR Plan. Ask your carrier which discounts are in its filing and what documentation it needs.

How much can I save with wildfire hardening?

Required discounts range from about 4% to 40% of the wildfire portion of your premium, with the largest going to the highest-risk homes. The FAIR Plan alone offers up to 16.4%. Your actual savings depend on your carrier's filing and which upgrades you complete.

What upgrades qualify for a wildfire insurance discount?

Most discounted items are structural: a Class A roof, WUI-listed ember-resistant vents, enclosed eaves, a noncombustible wall base, upgraded windows and a cleared Zone 0. Community programs such as Firewise USA can add a separate discount.

What documentation does my insurer need?

Dated photos of each upgrade, product listings for vents and materials, and a contractor's written summary of the work. We assemble that into one file you can send to your carrier or broker.

Free Hardening & Insurance Discount Assessment

45 minutes at your home. You get your official fire-hazard zone lookup, the 12-point discount audit, and a written report of what your property qualifies for — whether or not you hire us.

Or call (559) 550-6398